 Advertise



Disney (DIS) Stock Rally After Earnings Beat as Investors Weigh 2027 Outlook


Disney reported fiscal Q4 2026 revenue of $25.95 billion, up 16% year over year, while adjusted EPS of $1.77 topped Wall Street estimates.
Streaming subscription revenue increased 19% to $6.1 billion, while Experiences benefited from higher theme park attendance.
Disney expects double-digit adjusted EPS growth in fiscal 2027 and plans approximately $9 billion in share repurchases.
Disney (DIS) stock is back in focus after the company delivered a quarterly earnings beat and issued an upbeat growth outlook for fiscal 2027, giving investors fresh reason to reassess the stock. Revenue climbed 16%, supported by stronger performances across streaming, theme parks and sports, while management signaled further earnings growth ahead. But with content spending set to rise and shares approaching a key technical resistance level, the market faces a bigger test:
Can Disney’s latest results finally turn its recovery into a sustained rally?
Disney Revenue Jumps 16% as Earnings Beat Wall Street Estimates
Disney reported fiscal fourth-quarter revenue of $25.95 billion, compared with $22.46 billion a year earlier. Adjusted earnings reached $1.77 per share, exceeding analyst expectations of $1.67.
$DIS Disney Q4 FY26 (Sept. quarter):
• Revenue +16% Y/Y to $25.9B ($0.7B beat).
• Non-GAAP EPS $1.77 ($0.09 beat).
• Q4 benefited from an extra week.
📺 Streaming profit doubled to $824M.
💰 $9B in planned FY27 buybacks.
📈 Dividend raised by 33%. pic.twitter.com/1tSPLtCiVk— App Economy Insights (@EconomyApp) November 17, 2026
The improvement extended beyond the top line. Total segment operating income climbed 43% to approximately $5 billion, while income before income taxes increased 71% to $3.5 billion. The results highlight a stronger operating performance across Disney’s businesses, although the additional 53rd week in fiscal 2026 contributed to reported growth. Investors will therefore be watching whether the company can maintain its earnings momentum through the next financial year.
Streaming, Parks and Sports Strengthen Disney’s Business Mix
Disney’s streaming operations delivered one of the quarter’s strongest performances. Subscription revenue increased 19% to $6.1 billion, while streaming operating income more than doubled to $824 million from $402 million a year earlier. The Experiences division continued to provide a significant earnings contribution. Revenue reached approximately $10.1 billion, with operating income rising 20% to $2.25 billion. Global guest attendance increased 4%, indicating continued demand across Disney’s parks.
Sports also delivered stronger results. Revenue climbed 16% to $4.6 billion, while operating income increased 53% to $1.4 billion. The combination matters for Disney’s investment case. Streaming profitability is improving, parks remain a major earnings contributor, and sports continues to support the company’s broader entertainment strategy.
Disney’s 2027 Guidance: $9 Billion Buyback Meets Higher Content Costs
Disney’s fiscal 2027 outlook is now central to the stock’s investment narrative. Management expects double-digit adjusted EPS growth and approximately $11 billion in free cash flow. The company also plans to repurchase around $9 billion of its shares and increase its annual dividend by 33% to $2 per share.
However, the growth strategy requires heavier investment. Disney expects cash content spending to rise 9% to approximately $26 billion in fiscal 2027, reflecting continued investment in entertainment programming and sports rights.
Management also anticipates approximately 8% growth in total segment operating income. One change investors will need to assess is Disney’s decision to stop separately reporting streaming operating income. The company intends to place greater emphasis on its broader Entertainment segment, but the move will reduce visibility into the standalone profitability of streaming.
The key question is whether higher content investment can generate enough additional revenue and operating income to justify the spending.
Disney Stock Price Analysis: $120 Resistance Becomes the Next Test
Disney shares have been recovering within an ascending parallel channel since their July lows, according to the daily chart. The formation of higher highs and higher lows indicates improving buying momentum, with the stock gradually approaching the upper end of its previous trading range.
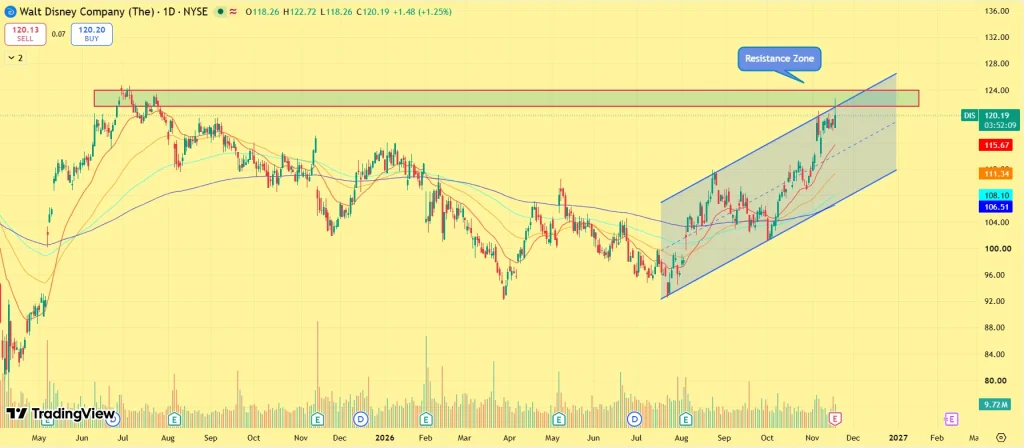
The immediate hurdle is the $116–$120 resistance zone. This area has previously attracted selling pressure, making it an important test for the current recovery. A decisive daily close above $122 could strengthen the bullish setup and signal that buyers are gaining control of the broader trend. It could also open the way for a move toward higher resistance areas.
However, another rejection would leave DIS vulnerable to a pullback toward the lower boundary of its rising channel. The moving averages currently provide support beneath the price, but a sustained move above resistance is needed to confirm a stronger breakout.
For DIS stock, the next test is whether the improved fundamentals can help shares clear the $120 resistance zone. A sustained breakout could strengthen the recovery narrative; another rejection would leave investors waiting for a clearer catalyst.
Was this writing helpful?

Trust with CoinPedia:
CoinPedia has been delivering accurate and timely cryptocurrency and blockchain updates since 2017. All content is created by our expert panel of analysts and journalists, following strict Editorial Guidelines based on E-E-A-T (Experience, Expertise, Authoritativeness, Trustworthiness). Every article is fact-checked against reputable sources to ensure accuracy, transparency, and reliability. Our review policy guarantees unbiased evaluations when recommending exchanges, platforms, or tools. We strive to provide timely updates about everything crypto & blockchain, right from startups to industry majors.
Investment Disclaimer:
All opinions and insights shared represent the author's own views on current market conditions. Please do your own research before making investment decisions. Neither the writer nor the publication assumes responsibility for your financial choices.
Sponsored and Advertisements:
Sponsored content and affiliate links may appear on our site. Advertisements are marked clearly, and our editorial content remains entirely independent from our ad partners.