 Advertise


JPMorgan Chase Stock Outlook Turns Bearish as Q3 Earnings Miss Wall Street Estimates


JPMorgan Chase stock faces downside pressure as third-quarter earnings and revenue miss analyst expectations.
Net income rises to $15.31 billion, but a securities loss and slowing dealmaking weigh on the results.
The $320–$325 support zone is the key technical level as investors assess whether the recent pullback will deepen.
JPMorgan Chase stock faces a bearish setup after the bank’s third-quarter results fell short of Wall Street expectations, putting pressure on its near-term outlook. Although net income increased year over year, earnings per share and revenue missed consensus estimates, while a slowdown in investment-banking activity raised questions about the sustainability of growth. JPMorgan’s trading business delivered stronger results, but that was not enough to prevent concerns over moderating client activity. With the stock approaching a crucial technical support zone, investors are now weighing the bank’s underlying resilience against the risk that earnings momentum could weaken in the coming quarters.
JPMorgan Earnings Miss Raises Fresh Concerns
JPMorgan reported third-quarter net income of $15.31 billion, up from $14.4 billion a year earlier. Earnings per share reached $5.57, below the $5.93 expected by analysts. Revenue increased 8% year over year to $50.17 billion but also missed the $51.23 billion consensus estimate.
A $658 million loss on investment securities added pressure to the results. More importantly, the earnings shortfall arrived alongside signs that some of the bank’s strongest businesses are losing momentum from the previous quarter. For investors, the concern is not simply that JPMorgan missed estimates. It is whether the bank can continue delivering the growth Wall Street has priced into its shares as market conditions and corporate activity change.
Slowing Deal Activity Puts Investment Banking Under Scrutiny
JPMorgan’s investment-banking fees rose 14% year over year but declined 8% from the second quarter. CEO Jamie Dimon said client activity in investment banking and markets had moderated from the previous quarter’s strong levels. That sequential slowdown is important because dealmaking and initial public offerings can provide substantial revenue for major banks. If companies delay listings or financing plans, investment-banking income could face additional pressure.
JPMorgan’s markets division offered a counterweight, with revenue increasing 15% year over year as volatility supported trading activity. Consumer banking also remained resilient, with net interest income rising 6% to $24.7 billion and average loans increasing 10%. However, strong results in these areas do not eliminate the risk that weaker dealmaking could slow overall earnings growth. Investors will be looking for evidence that the moderation is temporary rather than the beginning of a broader slowdown.
JPMorgan Chase Stock Price Analysis: Can Stock Defend $325 Support?
JPMorgan Chase stock has retreated sharply from its August peak near $370 and is attempting to stabilize around the $334–$338 area. The recent rebound has yet to reverse the broader short-term weakness, with the stock still trading below its declining moving averages.
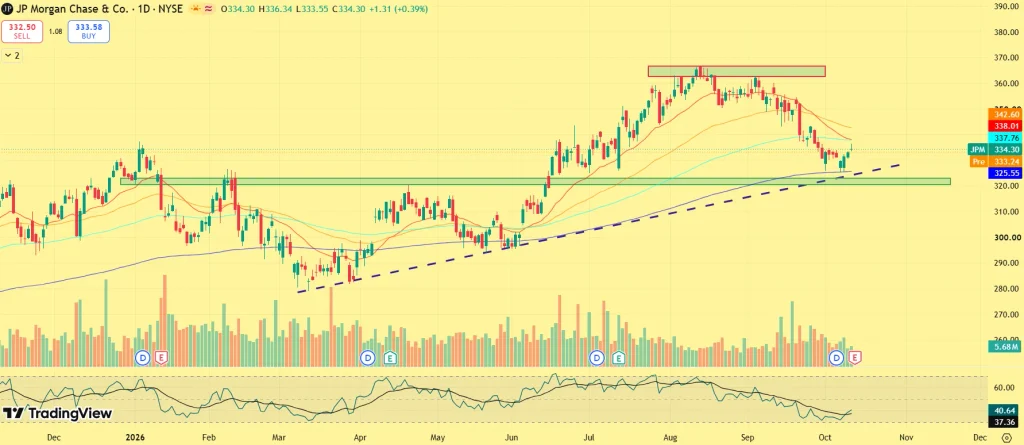
The $320–$325 support zone is the most important level on the chart. It aligns with a horizontal demand area and a rising trendline, creating a technical zone where buyers may attempt to defend the stock.
A decisive break below $320–$325 would weaken the chart structure and expose JPM to further downside. If that support holds, the stock could attempt a recovery, but it would first need to overcome resistance around $338–$342. A move above that band could open the way toward $350, although the bearish setup would not be invalidated by a brief intraday bounce alone.
Can Sellers Push the JPM Stock Price Below Support?
JPMorgan Chase stock faces a difficult test after third-quarter earnings missed Wall Street estimates and investment-banking activity showed signs of cooling. Higher year-over-year profits and stronger trading revenue provide underlying support, but they have not removed concerns about the bank’s growth trajectory. The technical picture adds another risk: a break below $320–$325 could deepen the pullback, while a recovery above $338–$342 would ease immediate selling pressure. Until either level is decisively breached, the balance of risks remains tilted to the downside.
Was this writing helpful?

Trust with CoinPedia:
CoinPedia has been delivering accurate and timely cryptocurrency and blockchain updates since 2017. All content is created by our expert panel of analysts and journalists, following strict Editorial Guidelines based on E-E-A-T (Experience, Expertise, Authoritativeness, Trustworthiness). Every article is fact-checked against reputable sources to ensure accuracy, transparency, and reliability. Our review policy guarantees unbiased evaluations when recommending exchanges, platforms, or tools. We strive to provide timely updates about everything crypto & blockchain, right from startups to industry majors.
Investment Disclaimer:
All opinions and insights shared represent the author's own views on current market conditions. Please do your own research before making investment decisions. Neither the writer nor the publication assumes responsibility for your financial choices.
Sponsored and Advertisements:
Sponsored content and affiliate links may appear on our site. Advertisements are marked clearly, and our editorial content remains entirely independent from our ad partners.